Insuring a Teen Driver Without Breaking the Bank
Adding a new driver is one of the biggest jumps in premium most families see. These strategies can help soften the impact.
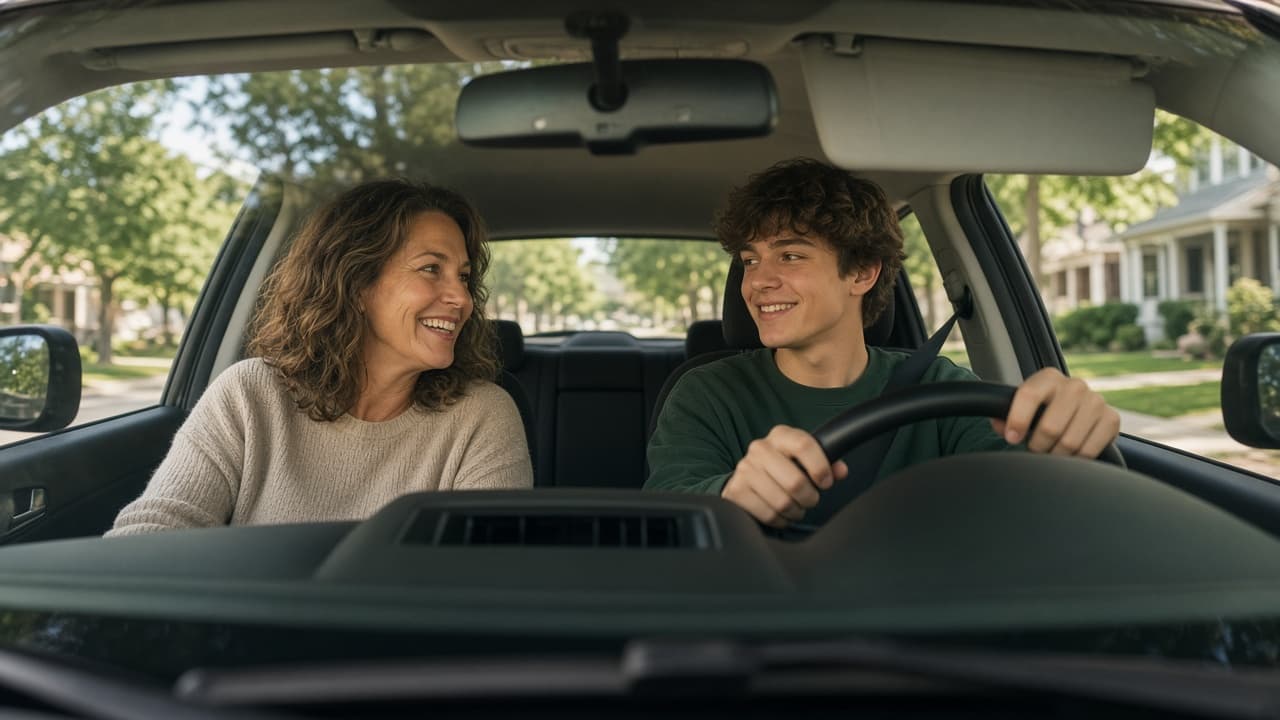
Handing over the keys to a new teen driver is a milestone, and for most families, a noticeable jump in insurance costs. Newer drivers statistically have more accidents, so insurers price that risk accordingly. The good news is there are several ways to manage the cost.
Add your teen to your policy (usually)
In most cases, adding a teen to an existing family policy is significantly less expensive than buying them a separate policy. You'll benefit from multi-car and other household discounts you've already earned. Check with your insurer about when your teen must be listed. Some require it at the learner's permit stage, others only once licensed.
Choose the right car
The vehicle your teen drives has a big effect on price. A used, mid-size sedan with strong safety ratings is generally far cheaper to insure than a new sports car or large truck. If the car is older and paid off, you might also consider whether collision and comprehensive coverage make sense.
Take advantage of student discounts
- Good student discount: often available for students maintaining a B average or equivalent.
- Driver training discount: for completing an approved driver's education or defensive driving course.
- Student away at school: if your teen attends college far from home without a car.
Try a usage-based program
Telematics programs that track driving behavior can reward safe habits, and the feedback can be a useful coaching tool for new drivers. Discuss expectations as a family before enrolling.
Raise deductibles, not risk
A higher deductible can lower your premium, but keep liability limits strong. A serious accident involving a new driver can be costly, and higher limits protect your family's assets.
Set clear family rules
Many parents use a written parent-teen driving agreement covering phone use, passengers, night driving, and seatbelts. Fewer incidents mean fewer claims, and better rates over time.
Shop around, especially now
Insurers price young drivers very differently. The company that offered your household the best rate before your teen was licensed may not be the most competitive afterward. This is one of the most important times to compare.
The bottom line
Adding a teen driver will likely raise your premium, but the right car, the right discounts, and comparing your options can make a meaningful difference. Get your personalized checklist to start comparing.
This article is for general educational purposes only and does not constitute insurance, legal, or financial advice. Coverage options, discounts, and rating rules vary by insurer and state. Consult a licensed insurance professional for advice about your specific situation.